Selling
Selling a Home in a Flood Zone in Cape Coral or Fort Myers: Disclosure, Insurance, and Pricing
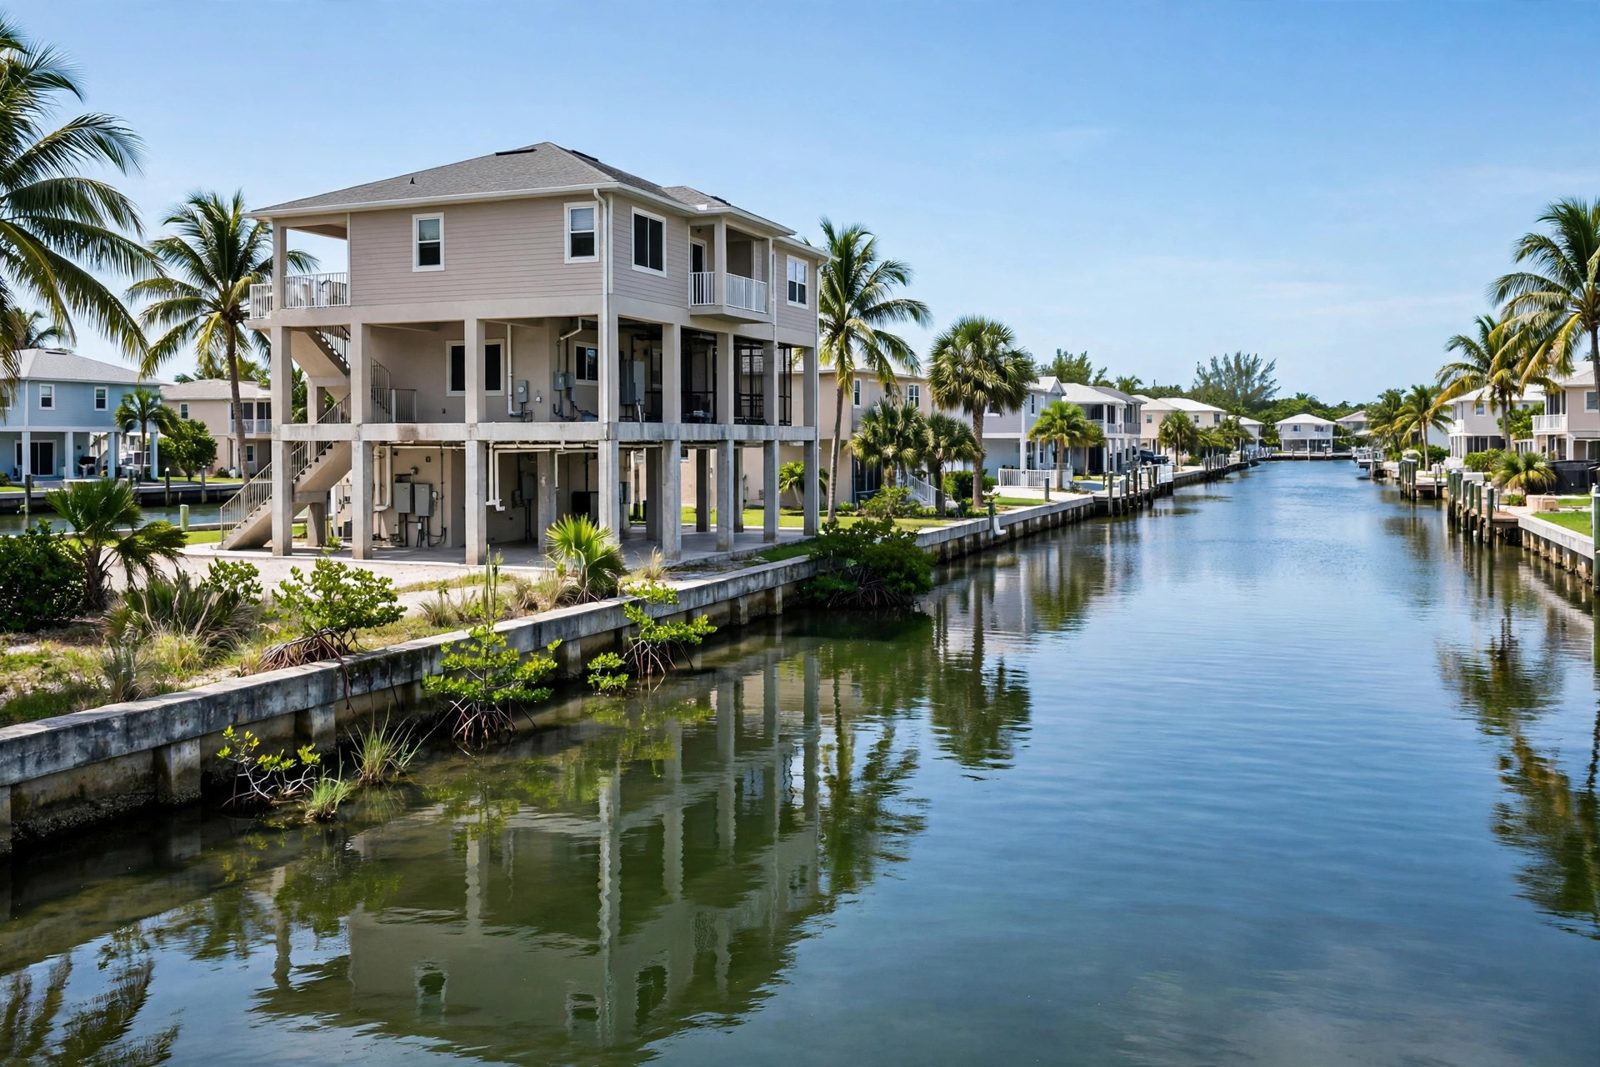
In Cape Coral, where canals put much of the city near water, and in Fort Myers along the Caloosahatchee and its creeks, flood zone designations are a normal feature of the map rather than an exception. Buyers know it, lenders know it, and insurers price it. What actually derails flood zone sales is not the designation itself but late discovery: a buyer who learns the real insurance cost or flood history after going under contract.
This guide covers the three things a seller controls: what you disclose, the documents you prepare, and how you price the insurance reality into the deal from the start.
Know your zone and your elevation before you list
Start with the FEMA flood map designation for your parcel and, more importantly, your elevation certificate if you have one. Two homes on the same Cape Coral street can sit at different elevations, and the certificate documents your home's actual height relative to the base flood elevation. That number drives flood insurance pricing more than the zone letter alone.
If you do not have an elevation certificate, getting one before listing is usually money well spent in a high hazard zone. It converts the buyer's worst assumption into a documented fact, and insurers can quote against it immediately instead of pricing your home at the pessimistic default.
What Florida sellers must disclose about flooding
Florida law now requires sellers to provide a flood disclosure covering whether they have filed flood damage claims, received federal flood assistance, or know of flooding that damaged the property. Separately, the general disclosure duty covers any known fact that materially affects value, which includes past water intrusion of any kind. Complete both honestly and completely.
In Fort Myers and Cape Coral, where Hurricane Ian flooding is part of the region's recent history, buyers and their agents will ask directly what happened to the home in the storm. A seller who answers with documentation, permits, and repair records keeps credibility. A seller who minimizes invites the buyer to assume the worst and price accordingly.
How flood insurance changes your buyer's math
If your buyer finances the purchase and the home sits in a special flood hazard area, their lender will require flood insurance. Premiums under the current federal pricing model are property specific and can range from manageable to severe depending on elevation, distance to water, and replacement cost. A buyer who budgets for a modest premium and is quoted several times that amount at the eleventh hour has a contract problem, and so do you.
Get ahead of it. If you carry flood insurance now, share your current premium information with serious buyers. If an assumable policy or a private flood option exists for the property, say so. The sellers who handle flood zone sales smoothly treat the insurance quote as part of the showing package, not as a closing week surprise.
Pricing a flood zone home honestly
Flood zone homes in Cape Coral and Fort Myers are priced against other flood zone homes, not against the elevated interior sale across town. Your competition is the canal home with similar elevation and water access, and buyers compare total monthly cost, including insurance, across that set. Price to the comparable set and the documented elevation, and let the water access do its work. Canal frontage, Gulf access, and a good dock still command premiums here; they simply carry an insurance line item that has to be visible in the math.
If your home has meaningful flood history, expect a negotiation about it and decide in advance what you will credit or repair. A planned concession offered early costs less than the same concession extracted after an inspection dispute.
Talk to Joseph
Flood zone sales in Cape Coral and Fort Myers are routine for sellers who prepare the documents and price the insurance reality in from the start. Call Joseph C. Brown of Epique Realty at (941) 677-5002 or email JoeBrown@Epique.me for a pricing analysis that uses your elevation and zone, not a generic map guess.
Questions sellers ask
Frequently asked questions
Do I have to disclose past flooding when I sell my Florida home?
Yes. Florida requires a specific flood disclosure about claims, assistance, and known flood damage, and the general disclosure law covers known water intrusion of any kind. Disclose completely and keep your repair documentation. Concealed flood history is one of the most common sources of post closing disputes in coastal Florida.
Will a flood zone designation stop a buyer from getting a mortgage?
No. Lenders finance flood zone homes routinely; they require flood insurance when the home sits in a special flood hazard area. The risk to your sale is not financing eligibility but a late, unexpectedly high insurance quote, which is why sharing premium information early matters.
What is an elevation certificate and should I get one?
It is a surveyor prepared document recording your home's elevation relative to the base flood level for your zone. Insurers use it to price flood policies precisely. If your Cape Coral or Fort Myers home is in a high hazard zone and you lack one, getting it before listing usually pays for itself in smoother quotes.
Does being in a flood zone lower my home's value?
It changes the buyer math rather than dictating a fixed discount. Buyers compare your total cost of ownership, including flood insurance, against similar homes. Strong water access, good elevation, and documented condition offset much of the zone effect, while surprises and missing documents deepen it.